Jul 2, 2026 | Economic News, Investment Property, Self Managed Super Fund (SMSF)
Important Notice: The measures discussed are proposed changes agreed between the Government and the Greens on 23 June 2026. The amendment is expected to pass the Senate in early July 2026 and commence 45 days after Royal Assent — approximately mid-August 2026. Seek professional advice immediately if you are mid-purchase or planning to purchase residential property in an SMSF.
What’s changing
On 23 June 2026, Prime Minister Anthony Albanese and Treasurer Jim Chalmers confirmed they have agreed to an amendment that will ban SMSFs from entering new limited recourse borrowing arrangements (LRBAs) to acquire residential property. The change was the price the Greens demanded for their Senate support of the Government’s broader Treasury Laws Amendment (Tax Reform No. 1) Bill 2026 — the legislation that overhauls the CGT discount and negative gearing rules.
This is a significant reversal of Labor’s previous position. As recently as May 2025, the Government stated it had “no intention” of banning LRBAs. That position has now changed.
What’s still allowed
Crucially, the ban is narrow in scope. Several SMSF property strategies remain fully available — and for many clients these alternatives will continue to be effective ways to hold property inside super.
- SMSF cash purchase — residential property: An SMSF with sufficient cash can still purchase residential property outright. No borrowing means the LRBA rules do not apply. The concessional tax treatment inside super remains — 15% on income, 10% on capital gains held more than 12 months, and 0% once the fund is in pension phase within the transfer balance cap.
- SMSF LRBA — commercial property: Borrowing to acquire commercial property (technically, “business real property”) remains available. This includes warehouses, offices, factories, and retail. The “business real property” test is specific — do not assume any non-residential property automatically qualifies. Get advice on the specific property you have in mind.
- Existing SMSF LRBAs — grandfathered: If your SMSF already has an LRBA in place for residential property, nothing changes. Existing arrangements continue under the current rules.
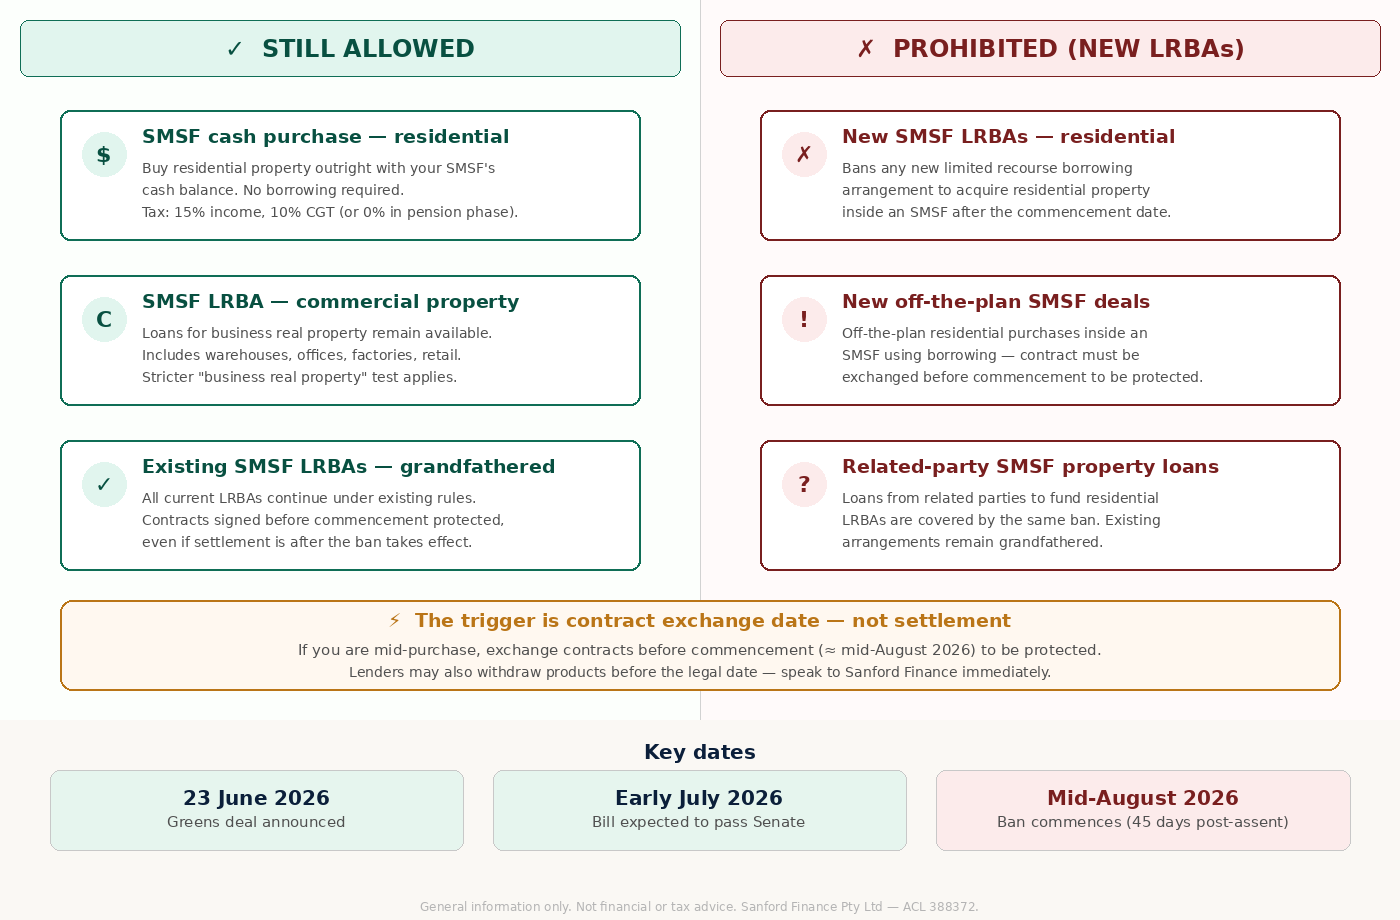
What’s still allowed vs. what’s prohibited under the proposed SMSF LRBA ban
The deadline that matters: contract exchange — not settlement
The legislation is explicit on this point. If you enter into an acquisition arrangement (exchange contracts) before the commencement date, you are protected — even if settlement happens after the ban takes effect.
The commencement date is 45 days after Royal Assent. The bill is expected to pass the Senate before the end of next week, putting the effective ban date in approximately mid-August 2026.
The commercial deadline is shorter than the legal one: The practical risk is not the legal deadline — it is the lenders. When Bill Shorten floated a similar policy in 2019, all four major banks withdrew their SMSF residential lending products before any law passed. We expect lenders to begin pulling SMSF residential products immediately. If you are mid-purchase, contact Sanford Finance now — not in August.
Who needs to act now
- Mid-process clients: If you are currently in the process of buying residential property inside your SMSF using borrowings, exchange contracts as quickly as possible.
- Off-the-plan buyers: Off-the-plan residential purchases inside an SMSF using borrowing must have contracts exchanged before commencement to be protected.
- Related-party loans: Related-party loan structures used to fund residential LRBAs are covered by the same ban. The same contract-date deadline applies.
Who is not affected
- Existing LRBA holders: If your SMSF already has an LRBA in place for residential property, the ban does not apply to you. Existing arrangements are fully grandfathered.
- Outright cash buyers: If you have sufficient cash in your SMSF to purchase residential property outright, you can proceed normally. The ban applies only to borrowing arrangements.
- Commercial property investors: Commercial LRBAs remain available, subject to the existing “business real property” rules.
What about the broader tax changes?
The wider Treasury Laws Amendment (Tax Reform No. 1) Bill 2026 — which overhauls the 50% CGT discount and tightens negative gearing — is now expected to pass the Senate before the end of next week. Importantly, superannuation, including SMSFs, was deliberately excluded from the CGT changes and continues to receive its existing concessional tax treatment — an effective 10% rate on realised capital gains, and a zero rate for retirees over 60 when the fund is in pension phase.
This means SMSFs holding residential property — whether purchased outright with cash or through an existing grandfathered LRBA — continue to enjoy a tax advantage relative to property held individually under the new rules.
Talk to Sanford Finance immediately: If you are mid-purchase, planning a purchase, or unsure how these proposed changes affect your existing structure, contact us today. We are already in discussion with our specialist SMSF lenders about product availability and timing. Call (02) 9095 6888 or visit sanfordfinance.com.au. Time is critical — the commercial deadline may be weeks ahead of the legal one.
Disclaimer: This article provides general information only and has been prepared without taking into account your objectives, financial situation or needs. The measures discussed are proposed changes agreed between the Government and the Greens on 23 June 2026 and are subject to passage through the Senate. This article does not constitute financial, tax or legal advice. Always seek advice from a qualified accountant, financial adviser or lawyer before making any decisions about your SMSF. Sanford Finance Pty Limited — Australian Credit Licence 388372 — ABN 50 117 771 187.

May 27, 2026 | Investment Property, Self Managed Super Fund (SMSF), Self Managed Super Fund (SMSF), Tax Planning
💡 The 2026 Budget didn’t change the SMSF property rules — but it made them significantly more attractive. Here’s why more investors are taking a serious look.
There are over 625,000 self-managed super funds in Australia, collectively holding more than $990 billion in assets. As the Budget makes established investment property less tax-effective for individual investors, the SMSF structure offers something the new rules can’t touch: a concessional tax environment built for the long term.
The Numbers at a Glance
SMSF rental income taxed at
15%
vs. up to 47% at individual marginal rates
CGT on assets held 12+ months
10%
vs. 30%+ minimum under new budget rules
CGT in pension phase
0%
within transfer balance cap ($2M for FY26)
SMSFs in Australia
625K+
holding $990B+ in total assets (ATO 2025)
The Tax Comparison is Compelling
TAX RATE COMPARISON — SMSF VS. INDIVIDUAL
Individual rental (top rate)
CGT new rules min (post-2027)
SMSF rental (accumulation phase)
CGT in SMSF (held 12+ months)
CGT in SMSF (pension phase)
Key takeaway: SMSF investors pay 15% tax on rental income vs. up to 47% individually — and just 10% CGT on gains vs. 30%+ under the new Budget rules.
*Within $2M transfer balance cap (FY26). General information only — not financial advice. Sanford Finance Pty Ltd — ACL 388372.
The Rules Haven’t Changed — But Your Opportunity Has
The Budget did not alter SMSF property investment rules. An SMSF can still purchase residential investment property using a Limited Recourse Borrowing Arrangement (LRBA), provided the fund meets the sole purpose test, the property is not occupied by any member or related party, and the investment aligns with the fund’s documented strategy. What has changed is the relative attractiveness of the SMSF path — because the alternative just became significantly more expensive.
Who Is SMSF Property Right For?
SMSF property is worth considering if you are:
- A high-income earner with a long investment horizon
- A business owner looking to hold commercial property in your SMSF
- Someone with an existing super balance above $200,000–$300,000
- Comfortable with the compliance requirements and illiquidity of property as an asset class
- Planning for retirement and wanting to maximise tax-free income in pension phase
What You Need to Know Before You Start
SMSF lending is a specialist product. Not all lenders offer it, and those that do apply stricter criteria — typically requiring a larger deposit, evidence of fund liquidity, and a minimum balance of $200,000–$300,000. The loan is assessed on the fund’s income, not the member’s, and the property must be held in a separate bare trust until the loan is fully repaid.
Division 296, which introduces a 30% tax on earnings above $3 million in super, passed Parliament in March 2026 and takes effect from 1 July 2026. For most clients this threshold is not a concern — but for those with larger balances, it is worth discussing structuring options with your adviser.
How Sanford Finance Can Help
At Sanford Finance, we work with specialist SMSF lenders and can help you assess whether this strategy suits your situation, structure the lending correctly, and ensure your investment meets ATO compliance requirements from day one. Talk to us before you move.
This article provides general information only and has been prepared without taking into account your objectives, financial situation or needs. Sanford Finance Pty Limited — Australian Credit Licence 388372. Always seek professional advice before acting.
May 27, 2026 | Economic News, Investment Property, Tax Planning
⚡ Time-sensitive: The grandfathering date is 12 May 2026. Properties purchased before that date are protected under the old rules. Speak to your Sanford Finance adviser before making any moves.
On Budget night — 12 May 2026 at 7:30pm — the goalposts shifted for Australian property investors. The changes announced by Treasurer Jim Chalmers will directly affect your tax position, your borrowing strategy, and potentially your retirement outcomes. Here is what changed, what stayed the same, and what you can still do before 1 July 2027 when the new rules take effect.
What Changed: Negative Gearing
From 1 July 2027, negative gearing will only be available on new residential builds. If you purchase an established investment property after Budget night, you will no longer be able to offset rental losses against your other income once the reforms commence. Properties purchased before 12 May 2026 are fully grandfathered — your existing portfolio is protected.
What Changed: Capital Gains Tax
The 50% CGT discount — which has allowed investors to halve their taxable capital gain on assets held more than 12 months — will be replaced by an inflation-indexed model with a minimum 30% tax on gains from 1 July 2027. For new builds, investors may choose between the 50% discount or the new arrangement. For established properties purchased after Budget night, the 50% discount will not apply to gains arising after 1 July 2027.
Before vs. After: At a Glance
| Policy Area |
Before Budget Night |
From 1 July 2027 |
| Negative gearing — established |
✓ Offset losses vs income |
✗ Abolished |
| Negative gearing — new builds |
✓ Available |
✓ Still available |
| CGT discount — established |
50% after 12 months |
Inflation-indexed + 30% min |
| CGT discount — new builds |
50% after 12 months |
Choose 50% or new model |
| Existing portfolio (pre-Budget) |
Current rules apply |
✓ Fully grandfathered |
| Commercial property |
Current rules apply |
✓ Appears unaffected |
The Real Dollar Impact: Tax on a $200,000 Capital Gain
EFFECTIVE TAX PAYABLE — $200,000 CAPITAL GAIN
Investor on 47% marginal tax rate, asset held 12+ months
Old rules
(50% CGT discount)
New rules (post-2027)
(30% minimum tax)
No discount
(full marginal rate)
Key takeaway: The new rules add over $13,000 in extra tax on a single $200,000 gain compared to the old 50% discount.
Illustrative only. General information — not financial advice. Sanford Finance Pty Ltd — ACL 388372.
For an investor on a 47% marginal tax rate selling an established property with a $200,000 capital gain held more than 12 months: under the old rules with the 50% discount, tax payable was $47,000. Under the new rules from 1 July 2027, the minimum tax payable rises to $60,000 or more — that is over $13,000 more going to the ATO on a single sale.
What This Means for Your Strategy
For investors with existing portfolios, the news is good — nothing changes. For those looking to grow, the calculus has shifted significantly. New builds now carry a structural tax advantage over established properties. Commercial property may emerge as an attractive alternative as it appears unaffected by the reforms. SMSF structures — which have their own concessional tax environment — also become considerably more compelling.
Before making any moves, speak with your Sanford Finance adviser. The interaction between these changes, your income, your existing holdings, and your loan structure is complex — and the right strategy will look different for every client.
This article provides general information only and has been prepared without taking into account your objectives, financial situation or needs. Sanford Finance Pty Limited — Australian Credit Licence 388372. Always seek professional advice before acting.